01
Fixed venues
Coverage shaped around lanes, participants, spectators, employees, your lease, and the property inside your doors.
- Participant treatment
- Buildout and income
- Lease limits
Insurance for the sharp end of entertainment
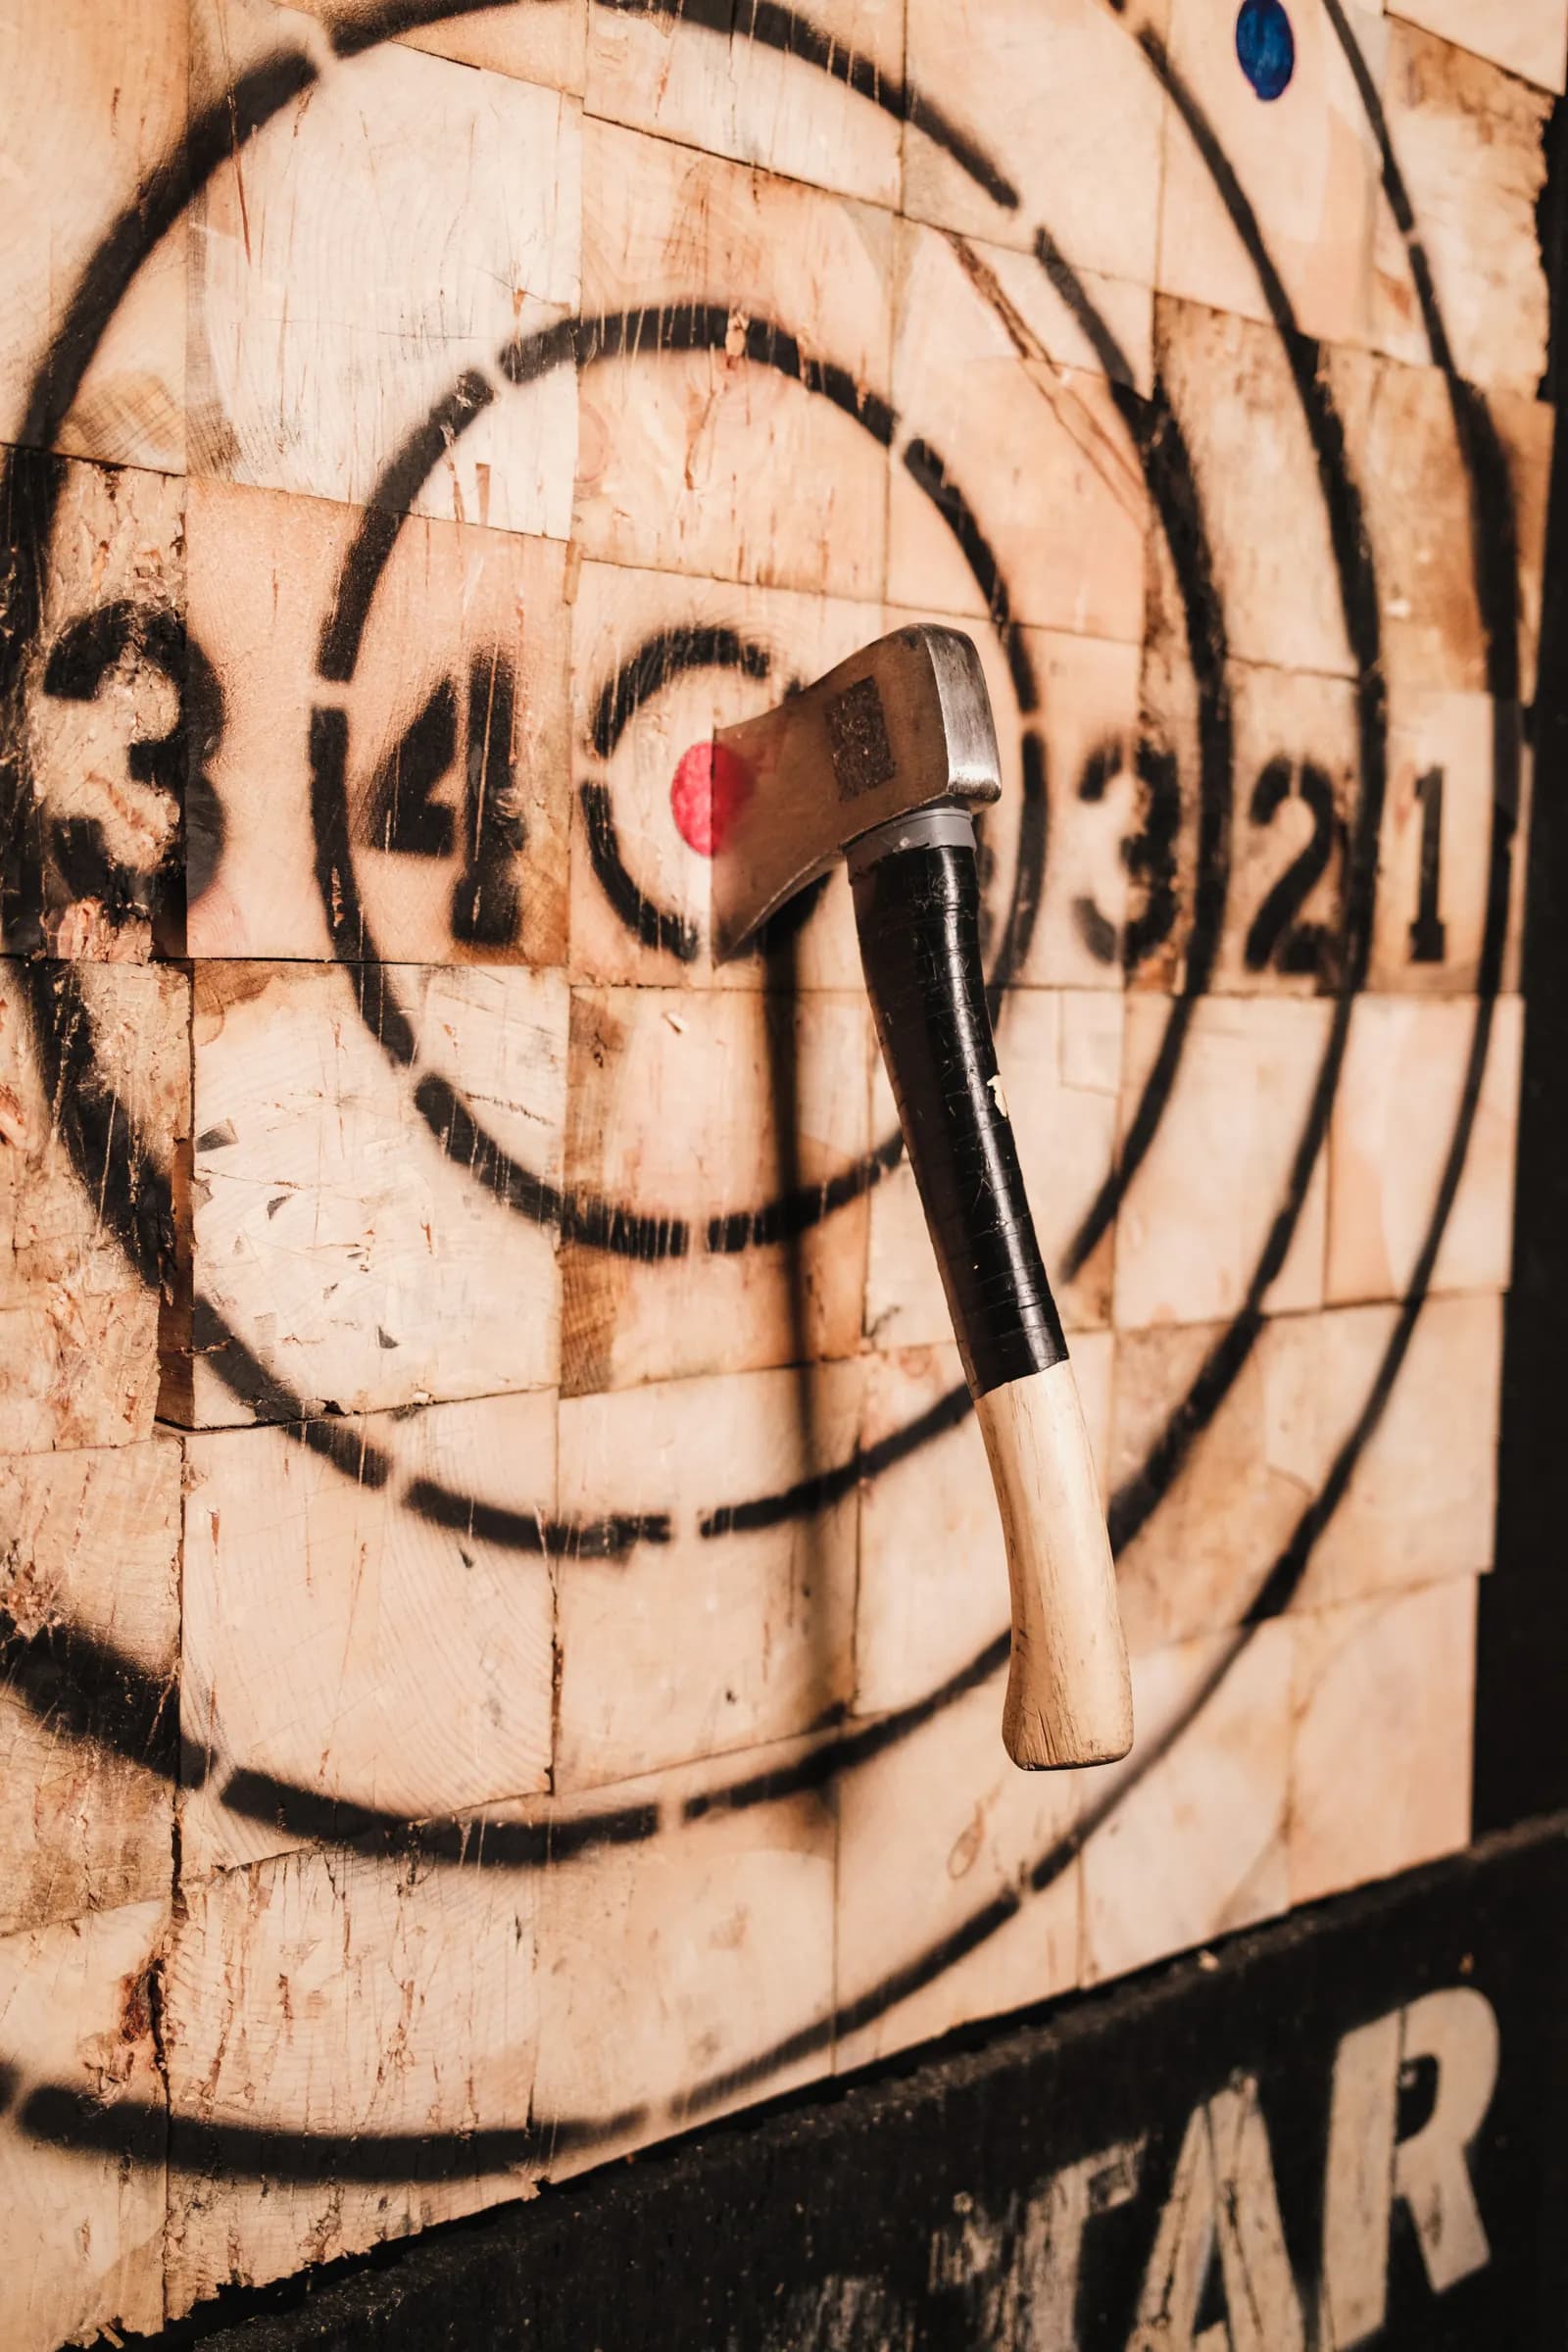
Fixed venue, mobile trailer, BYOB, or multiple attractions—we help you examine the details that can decide whether a policy actually fits your operation.
The policy details that matter here
Your operating model comes first
We start with how your customers participate, where you set up, and what else happens around the throwing lanes—not a generic business category.
Coverage shaped around lanes, participants, spectators, employees, your lease, and the property inside your doors.
Protection that considers where your trailer goes, how the range is enclosed, and what event contracts require.
Alcohol sales, service, and bring-your-own rules each deserve an explicit answer—not an assumption.
Axe throwing alongside rage rooms, escape rooms, laser tag, archery, or food service needs a complete submission.
Read beyond the declarations
A certificate can prove that a policy exists. It cannot tell you whether the activities that make your venue unique are restricted or excluded.
Start my policy checkThe participant check
Some forms can restrict or exclude injuries to people taking part in the activity. The policy should answer this directly.
The location check
A fixed-location policy may not follow a mobile range to a brewery, fair, private party, or corporate event.
The alcohol check
Each creates different underwriting and liability questions. Disclose the real operating model before binding.
The contract check
Landlords and event partners may require specific limits, additional insured status, and an occurrence-based form.
Build the coverage stack
Your final program depends on underwriting, state rules, contracts, and policy terms. These are the areas most operations should review together.
Claims involving guests, participants, spectators, and staff.
The venue, improvements, contents, and interruption exposure.
Vehicles, trailers, gear, and liability away from the venue.
Where claims can begin
These examples are illustrative. Whether coverage responds depends on the facts and the policy's terms, conditions, and exclusions.
Prepare for underwriting
A clear submission helps carriers understand your controls and reduces avoidable questions while you are trying to open, renew, or satisfy a contract.
Locations, lanes, targets, hours, participant volume, revenue streams, mobile events, and additional attractions.
Minimum age, waivers, lane supervision, coach training, first aid, barriers, maintenance, and alcohol procedures.
Years operating, prior insurance, claims, cancellations, payroll, property values, and the limits your contracts require.
Revenue and participant volume, fixed versus mobile work, alcohol, additional attractions, property values, payroll, required limits, location, controls, operating history, and prior claims.
Get pricing for my operationA straightforward path
Start with your ZIP and preferred contact method.
Venue, mobile work, alcohol, activities, people, and property.
Compare policy structure, limits, terms, and price.
Questions from the range
Every operation is different. These answers are starting points, not a substitute for reviewing your actual policy.
Not automatically. Policy wording varies, and some forms restrict or exclude participants. Ask for a review that specifically confirms how customers are treated while they are throwing.
No. A professionally drafted and consistently collected waiver is an important risk control, but it does not stop every claim or replace insurance. Have an attorney familiar with your state review it.
New ventures may qualify. Underwriters commonly ask for lane plans, supervision procedures, training, waivers, participant ages, projected revenue, alcohol details, and every additional attraction.
Potentially. The policy must contemplate off-premises operations. Expect questions about the trailer, enclosure, setup process, towing vehicles, event types, storage, supervision, and participant separation.
BYOB should always be disclosed and addressed explicitly. The appropriate protection depends on state law, your controls, and the policy wording. Do not assume general liability handles every BYOB incident.
Carriers may consider revenue and participants, fixed versus mobile work, alcohol, other attractions, property values, payroll, limits, location, safety controls, operating history, and prior claims.
Ready when you are.